The current mortgage interest deduction is $1 million. The House version of the tax bill called for a $500,000 cap while the Senate left it untouched. They split the difference and capped it at $750,000. Congress is expected to pass H.R. 1 this week


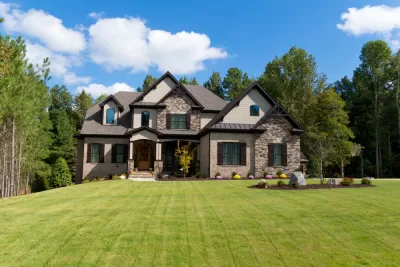
The final version of H.R. 1: Tax Cuts and Jobs Act, caps the mortgage interest deduction (MID) at $750,000 for those who itemize their taxes, estimated at 30 percent of the population in 2013, according to the IRS. Those who benefit from the MID are even fewer–about 20 percent of the population.
As a result of the MID reduction and reducing the state and local tax (SALT) deduction (also see Vox description), which includes property taxes paid by homeowners, to $10,000, H.R. 1 can be expected to increase many homeowners’ monthly housing costs, writes Conor Dougherty, an economics reporter at The New York Times, on Dec. 16.
According to Zillow researcher, Alexander Casey, the amount of homeowners affected by the loss of the two homeowner deductions will be substantial. Currently, 44 percent of homeowners claim the MID. With the bill's passage, which includes doubling the standard deduction, as expected by Friday, that percentage drops by almost 30 percent to 14.4 percent.
Broad support for ending or lowering mortgage interest deduction
"[H]omeowner subsidies, in particular the mortgage interest deduction, [are] one of the rare tax breaks with critics across the political spectrum," notes Dougherty. Many economists, including Harvard University's Edward Glaeser, author of Triumph of the City, support ending the mortgage interest deduction because of its effect on the housing market, the urban landscape, and social equity.
Since the benefits of these deductions get bigger with larger and more expensive homes, the bulk of the benefits accrue to wealthier homeowners in pricier markets. This alters the landscape by encouraging more single-family homes and suburban sprawl. That, in turn, prompts the government to spend more on roads and infrastructure and makes housing a bigger portion of the economy than it would be in the absence of federal help.
On the other hand, look at the benefits of home ownership, which the MID must surely help achieve, or does it?
"Costing at least $70 billion a year, the mortgage interest deduction is one of the largest federal tax expenditures, but it appears to do little to achieve the goal of expanding homeownership," notes a 2013 Center on Budget and Policy Priorities paper.
The main reason is that the bulk of its benefits go to higher-income households who generally could afford a home without assistance...
Meanwhile, close to half of homeowners with mortgages — most of them middle- and lower-income families — receive no benefit from the deduction. Three major bipartisan panels have proposed to convert the deduction to a credit and lower the maximum amount of interest it covers.
"Matthew Desmond, a Princeton sociologist who studies how eviction wreaks havoc on the lives on the poor, has documented how the deduction became the 'engine of American inequality' because it favors higher-income homeowners," adds Dougherty.
Yet Dougherty reminds us that "[b]oth parties have long championed homeownership as a way to help people build wealth and keep neighborhoods more stable."
Losing the MID fight were realtors. "The final tax reform bill released punishes homeowners and weakens homeownership," the California Association of Realtors said in a statement issued on Dec. 15.
Not affected by the MID reduction are homeowners with existing mortgages, which won't be helpful in terms of increasing inventory, notes Dougherty.
By allowing homeowners already benefiting from the existing mortgage interest deduction cap to keep it, the bill is likely to encourage people to stay in place a bit longer.
Dougherty includes many other of the far-reaching aspects of how the mortgage interest deduction has become "so entrenched in the social fabric that [it has] become [an] entitlement in all but name."
Hat tip to Eric Gilbertson.
FULL STORY: Homeowners Have Had It Good. Too Good, Says the Tax Bill.

Op-Ed: It's Time for a Weakened Mortgage Interest Deduction To Go
Last year's tax reform bill seriously curtailed the mortgage interest deduction, despite its reputation for untouchability. Perhaps lawmakers should get rid of it entirely.
More Fallout on Affordable Housing from Tax Bill
While the low income housing tax credit was retained, banks will be much less willing to purchase them due to their reduced corporate tax rate. That's just one way H.R. 1 will exacerbate divisions between the rich and poor in America's cities.
Tax Reform and the Housing Market
Curbed analysis of how local and regional housing markets will react to changes to the country's tax code.

Planetizen Federal Action Tracker
A weekly monitor of how Trump’s orders and actions are impacting planners and planning in America.

The state-sanctioned urbicide of Austin
People don’t kill cities. Freeways do.

US to reduce Colorado River water deliveries to Mexico
A new Colorado Treaty amendment reduces Mexico’s Colorado River water allocation by 250,000 acre feet.

5 New England states march closer to 800 megawatt wind energy project
Securing federal approval for the project may be complicated under the Trump administration, which has historically been hostile towards domestic wind power.

Baltimore to break ground on $50 million Transit Priority Project
The project will bring faster bus trips, safer streets and better bike connections to Baltimore.

Airbnb launches $250 million 'last-dollar financing' housing accelerator, makes first investment in Austin
The company will put $6.4 million towards affordable housing development in Texas’ capital.

FREE Course: Walkable City 1: Why Walkability?
After describing his path towards focusing on walkability as the essence of good planning, Jeff Speck marches through his five principal reasons for making more walkable places.
Reinventing Malls: Planning Alchemy—Turning Gray Fields Into Gold
The course focuses on the opportunities and imperatives that shape reinvention of mall sites.

Eagle County Government
Harvard University Graduate School of Design
Nashville Planning Department
The Architects Foundation
University of Cincinnati Online
The Pocatello Development Authority
The Urban Renewal Agency of the City of Pocatello
Journal of the American Planning Association