Fannie Mae and Freddie Mac will deliver $10.2 billion in dividends to the U.S. Treasury next month, but Congress could soon "wind down" the companies by approving the significant Johnson-Crapo bill.


The next few weeks and months will determine the future (or lack thereof) for government-backed mortgage finance companies Fannie Mae and Freddie Mac.
First comes news that the two companies recently sent their profits to the U.S. Treasury under terms of their bailout deal from 2008.
Maggie McGrath reports on the first quarter profits of the companies: "Fannie Mae posted $5.3 billion in net income for the first quarter of 2014 and comprehensive income of $5.7 billion, the company’s ninth consecutive quarterly profit though a notable downturn from the $58.7 billion reported as net income in the year-ago period. The difference is largely attributable to a one-time accounting move that allowed Fannie Mae to apply losses from delinquent mortgages."
"Freddie Mac, meanwhile, reported $4 billion in net income, down $4.6 billion from the prior-year period thanks to derivative losses and lower legal settlement proceeds. The company’s comprehensive income came in at $4.5 billion, and like Fannie Mae, that figure is heading straight into the hands of Uncle Sam. After this dividend is paid in June, Freddie Mac will have repaid the Treasury a total of $86.3 billion, a sum that’s nearly $15 billion higher than the $71.3 billion it borrowed."
The earnings are a temporary blip, however, and not a long-term trend toward profitability. An article by Nick Timiraos and Eliot Brown quotes Jim Vogel, a debt-market analyst at FTN Financial, to describe Fannie and Freddie's long-term prospects: "Bottom line, Fannie and Freddie are not inherently profitable operations in any conventional sense beyond the next couple of years." Given that uncertainty, Congress is expected to vote soon on legislation—the so-called Johnson-Crapo bill—that could break the mortgage giants up.
Bendix Anderson writes of the possible implications of the legislation on multi-family lending. "The Johnson-Crapo bill proposes replacing Fannie Mae and Freddie Mac...with a new and independent federal agency called the Federal Mortgage Insurance Corp. (FMIC)," explains Anderson. "The final impact for multifamily borrowers might be slightly higher interest rates for multifamily loans provided under the new FMIC loans that would replace the Fannie Mae and Freddie Mac program loans."
In a separate report, Alexander MacLennan discusses the Johnson-Crapo legislation as well as a recent stress test that found the companies to be at risk of $190 billion in losses in the event of another downturn.
Finally, an editorial by Harry Alford calls for Congress to reform Fannie and Freddie rather than killing them. According to Alford, "with Johnson-Crapo, Congress is threatening to jeopardize that stability and undo years of resilience from American taxpayers."
Read the full story: Fannie Mae And Freddie Mac Sending Treasury $10.2 Billion After Posting First Quarter Profits
The Underappreciated Role of Freddie Mac and Fannie Mae in Access to Affordable Housing
A housing researcher formerly with the Obama administration's Treasury Department explains the role of government-sponsored enterprises in opening the housing market with more affordable options.
Is this Closure? Bank of America Settles with FHFA for $9.3 Billion
The Federal Housing Finance Agency (FHFA) announced a $9.3 billion settlement with Bank of America following a 2011 suit tied to the bank’s role in selling faulty mortgage-backed securities to Fannie Mae and Freddie Mac.
Letting Fannie and Freddie Off the Hook
Although they played a part in the ensuing financial panic, noted economist Mark Zandi argues why Fannie Mae and Freddie Mac don't deserve to be blamed for the housing bubble.
Planetizen Federal Action Tracker
A weekly monitor of how Trump’s orders and actions are impacting planners and planning in America.
Amtrak, CN end decades-long dispute with eight-year agreement
The new operating agreement establishes an updated framework for the companies to work together, including processes to resolve disputes.
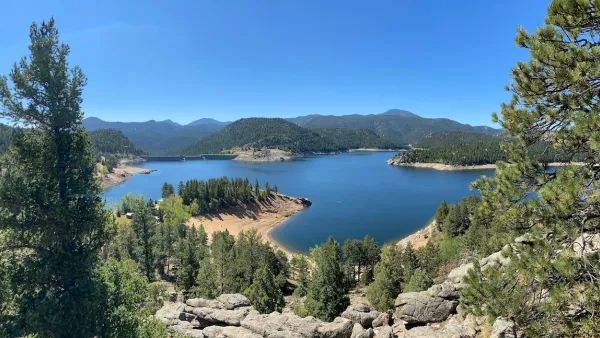
Judges permit Denver to divert 77,000 acre feet from the Colorado River for reservoir expansion
Overuse and climate change have caused the Colorado River’s water levels to plummet.
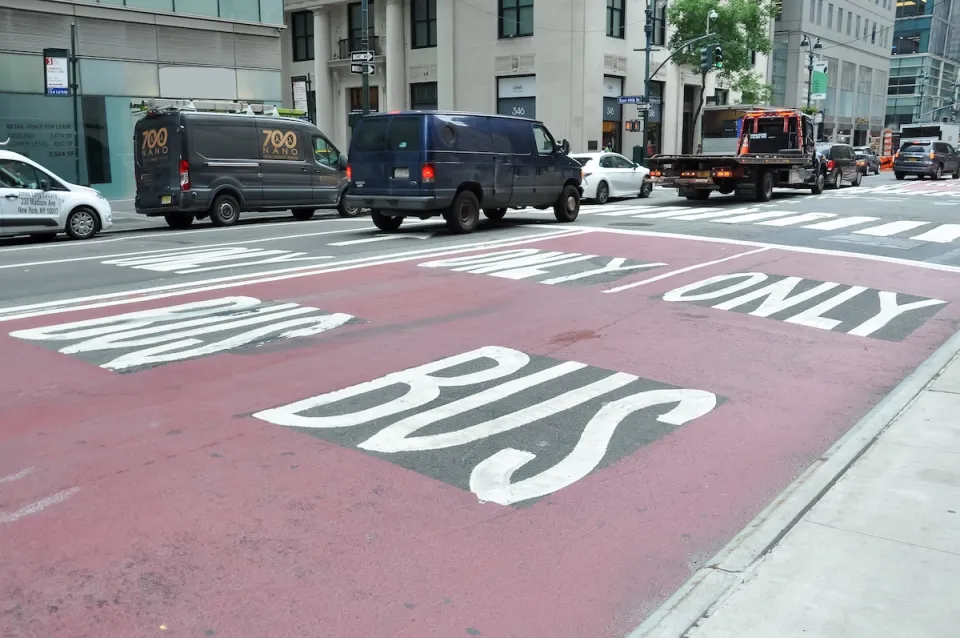
NYC DOT wants faster, more permanent street upgrades
The city is examining ways to build more concrete infrastructure without getting entangled in 'decades-long' projects.

'Something we’ve never seen before:' rising utility rates could strain city finances nationwide
Data centers, climate change and other factors have caused utility rates in the United States to increase by 38% since 2020.

Trump to overrule local leaders, lease millions of acres of America’s Pacific Island territories’ seafloors to mining companies
International law says that the Indigenous people of America’s territories have a right to prior and informed consent regarding projects that impact their countries.
FREE Course: Walkable City 1: Why Walkability?
After describing his path towards focusing on walkability as the essence of good planning, Jeff Speck marches through his five principal reasons for making more walkable places.
Reinventing Malls: Planning Alchemy—Turning Gray Fields Into Gold
The course focuses on the opportunities and imperatives that shape reinvention of mall sites.

Harvard University Graduate School of Design
KFH Group Inc.
Greater Baltimore Committee
The Architects Foundation
University of Cincinnati Online
The Pocatello Development Authority
The Urban Renewal Agency of the City of Pocatello