A company owned by Berkshire Hathaway has been been indulging in some of the same tactics that led to the larger housing crisis about ten years ago.


By Doug Ryan
Earlier this month, the Center for Public Integrity and The Seattle Times released an investigative article examining the business practices of the leading manufactured home builder, lender, and retailer, Clayton Homes. As many readers now know, Clayton, a Berkshire Hathaway firm, operates the two largest lenders, the biggest retail network, and the top manufactured home builder in the nation.
What may have come as a surprise, though, is how the practices highlighted in the article seem to be a replay of those that led to the larger housing crisis about ten years ago—misleading loan terms, underwater homeowners and questionable practices that look a lot like steering.
The article also digs into many of the practices that CFED and its partners have highlighted as damaging to low- and moderate-manufactured homeowners—questionable sales practices, misleading lending terms, and expensive loan products—all of which can make a family’s key asset, their home, a depreciating one. For better or worse, Clayton is an obvious target for this type of journalism. It is an integrated company with a national footprint that makes about 40 percent of all manufactured home loans—and 45 percent of all the homes. For years, other lenders and retailers have operated in similar ways.
The article underscores why Congress and this Administration must hold fast on manufactured housing finance reform and not undercut the lending regulations that the Consumer Finance Protection Bureau (CFPB) implemented in early 2014. These rules have had about 15 months to work and there is little, if any, public evidence that access to credit has been hindered. Moreover, the CFPB has the authority to revisit the rules in response to market conditions and has decided not to do so.
CFED recently wrote about why the arguments for H.R. 650 and its Senate companion, S. 682, two bills to roll back protections for manufactured home buyers, are not supported by evidence and would be harmful to consumers, and why it is critical that we continue to work together to mainstream manufactured housing into the marketplace. Until owners of manufactured homes have the same broad rights and expectations in the housing marketplace, their homes will never be considered truly part of the affordable housing solution.
Ever since versions of these bills first appeared in Congress in 2012, insiders have argued that they are needed because the CFPB rules would be the death of the industry. That’s demonstrably untrue. Data from January 2015 show a one-year home production increase of 14 percent, suggesting the industry is finding new buyers. Furthermore, Berkshire Hathaway reported that Clayton experienced a remarkable 34 percent earnings growth in 2014.
These rules, some have argued, prevent lenders form making loans less than $20,000, due to high fixed costs. Yet the industry, in an apparent contradiction, recently introduced a new manufactured housing product, TruMH, which costs less than that magic threshold. (Yes, there are other fees that raise the final costs over $20,000, and there are cash sales, but it seems counterproductive to release a new product that does not fully support the industry’s lending arm, which is the real moneymaker in this space.)
No doubt in light of these trends, industry and its Congressional allies have retooled the talking points to claim that the legislative fix is aimed at helping low- and moderate-income homebuyers squeezed by nefarious Washington bureaucrats. To take this argument to its logical end, consumers would be better served if we simply return to the days of manufactured home lending in the shadows. Sadly, the experiences of the families highlighted in the Seattle Times/CPI story are such because they borrowed in the era before Congress introduced sunlight to this part of the housing world.
Another interesting part of this story is that...
Read the full story: Article Reveals Manufactured Housing Industry’s Greed
Should the public sector buy mobile home parks?
One writer argues that the crisis facing the nation's mobile home owners warrants public intervention.
The Role of the Government in Home Loans
The Freddie Mac/Fannie Mae crisis is resurrecting the debate over the role the federal government should play in the housing market.
The Incredible Shrinking Home
A new AIA report shows that new homes under construction are getting smaller in response to market forces.
Planetizen Federal Action Tracker
A weekly monitor of how Trump’s orders and actions are impacting planners and planning in America.
Amtrak, CN end decades-long dispute with eight-year agreement
The new operating agreement establishes an updated framework for the companies to work together, including processes to resolve disputes.
Judges permit Denver to divert 77,000 acre feet from the Colorado River for reservoir expansion
Overuse and climate change have caused the Colorado River’s water levels to plummet.
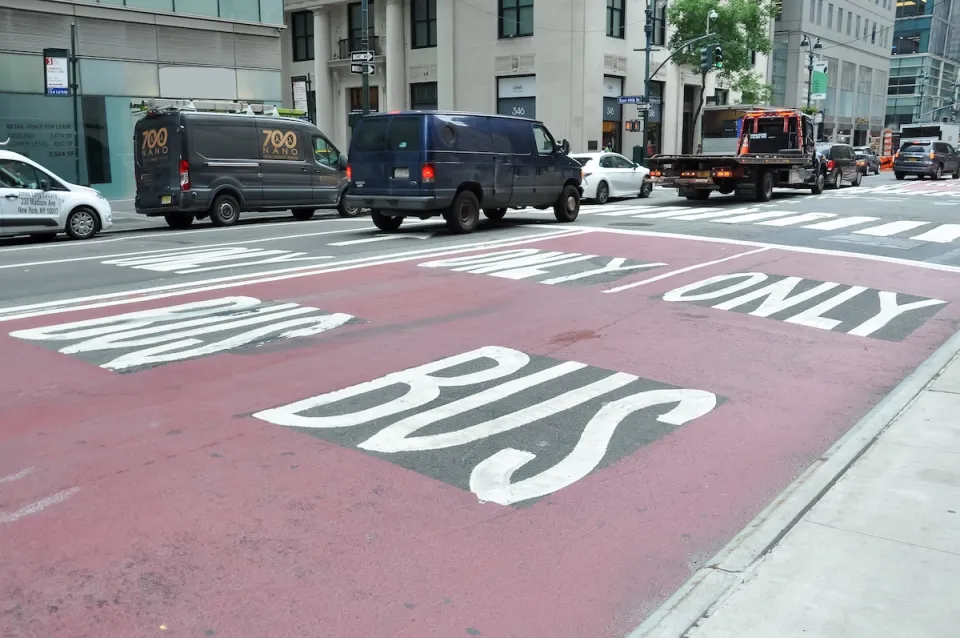
NYC DOT wants faster, more permanent street upgrades
The city is examining ways to build more concrete infrastructure without getting entangled in 'decades-long' projects.

'Something we’ve never seen before:' rising utility rates could strain city finances nationwide
Data centers, climate change and other factors have caused utility rates in the United States to increase by 38% since 2020.

Trump to overrule local leaders, lease millions of acres of America’s Pacific Island territories’ seafloors to mining companies
International law says that the Indigenous people of America’s territories have a right to prior and informed consent regarding projects that impact their countries.
FREE Course: Walkable City 1: Why Walkability?
After describing his path towards focusing on walkability as the essence of good planning, Jeff Speck marches through his five principal reasons for making more walkable places.
Reinventing Malls: Planning Alchemy—Turning Gray Fields Into Gold
The course focuses on the opportunities and imperatives that shape reinvention of mall sites.

Harvard University Graduate School of Design
KFH Group Inc.
Greater Baltimore Committee
The Architects Foundation
University of Cincinnati Online
The Pocatello Development Authority
The Urban Renewal Agency of the City of Pocatello