Scrambling to grab that elusive “American Dream” of homeownership, millions plunged into the subprime mortgage market to build wealth through appreciation (if not speculation). Pundits cheered as the ownership rate crept up, lauding the pluck of aspirational minority and immigrant families.There’s a reason it is called subprime, though. Lenders offered a smorgasborg of loan “products,” but the bottom line was that they are all very costly for the borrower – often entailing adjustable-rate surprises in the 30 percent or higher range.


Scrambling to grab that elusive "American Dream" of homeownership, millions plunged into the subprime mortgage market to build wealth through appreciation (if not speculation). Pundits cheered as the ownership rate crept up, lauding the pluck of aspirational minority and immigrant families.
There's a reason it is called subprime, though. Lenders offered a smorgasborg of loan "products," but the bottom line was that they are all very costly for the borrower – often entailing adjustable-rate surprises in the 30 percent or higher range.
With prices flat and interest rates creeping up, defaults on subprime loans are skyrocketing, with many borrowers falling behind after just a few months. The lenders who have not yet filed for bankruptcy are stampeding to the exits. A great number of them, though, took billions out of these businesses before they went belly-up.
the real cost will be born by the borrowers, who have no financial cushion. They had hoped that home appreciation would build some wealth. Wages, by and large, have not done the job even with a growing economy.
Their communities will also pay. A lot of those subprime buyers have snapped up the little ranches and Cape Cods in the 1950s inner suburbs, giving a new lease on life to communities that professionals and more affluent buyers have skipped over. Though the houses in these cul de sacs can still look neat, with their hedges and lawns nicely clipped, many of these communities have stagnated, sunk into poverty, or hovered at the tipping point for years. Even modest appreciation would solidify middle-income status for struggling wage earners, but the outlook now is for slippage, possibly long-term price drops.
As the pain spreads, there will be much handwringing and fingerpointing (assuming it does not incite a broader market meltdown as some fear). But the warning bells were rung early and often. No one in Congress, at Freddie Mac, Fannie Mae, or in the mortgage industry should have been unaware of the lax regulation and the likelihood of high levels of defaults. But the pickings were too lush, and the lobbying largesse was spread too thick.
And when things stabilize, the mess will get swept under the rug, because, after all, maybe a few hundred thousand borrowers, or a few million – as in the similarly greed-driven savings and loan collapse in the late 1980s – will be hurt, and they'll be largely invisible because they don't stroll the board rooms of banks or live in the nice neighborhoods of media executives.
There used to be names for this kind of thing, though. One was fraud and the other was usury. Maybe our language will be enriched by them again.
Just 17% of San Diego households can afford the city's $1M+ median home prices
The city is becoming increasingly unaffordable to prospective homebuyers.
Report: Housing is becoming an 'inherited advantage'
As housing costs soar, buying a home is becoming unaffordable to a large swath of American families.
'Starter' homes cost over $1M in 242 US cities
Once concentrated in coastal regions, cities with starter homes valued at over $1 million are now spread across 26 states.
Planetizen Federal Action Tracker
A weekly monitor of how Trump’s orders and actions are impacting planners and planning in America.
California plans to bury El Niño’s downpour
If the state plays its cards right, it may be able to store a billion acre-feet of El Niño’s water in aquifers.
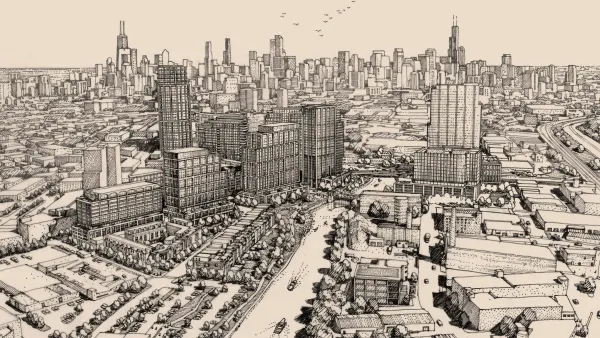
Chicago breaks ground on $3 billion megadevelopment
The new neighborhood, titled Foundry Park, will one day host 3,700 residences.

California High-Speed Rail Authority CEO resigns after $600,000 scandal
Under Ian Choudri, the authority used taxpayer dollars to fund first class flights and trips to nightclubs.

Want to study the Missouri River? Soon, you may need unanimous approval from 10 states
Legislation would require 10 governors’ permission to study or build projects moving water outside the basin.

Desperate measures: Advocates weigh draining Lake Powell to fill Colorado River
Draining the reservoir could reduce evaporation losses by a couple hundred thousand acre-feet.
FREE Course: Walkable City 1: Why Walkability?
After describing his path towards focusing on walkability as the essence of good planning, Jeff Speck marches through his five principal reasons for making more walkable places.
Reinventing Malls: Planning Alchemy—Turning Gray Fields Into Gold
The course focuses on the opportunities and imperatives that shape reinvention of mall sites.

City of Rosemead
Rutgers University, Edward J. Bloustein School of Planning and Public Policy
One Hundred Miles
Hunter College, City University of New York (CUNY)
The Architects Foundation
University of Cincinnati Online
City of Cambridge
Montrose County
The Pocatello Development Authority

